What is CKYC (Central KYC)?


Table of Content
You open a bank account, complete your KYC and move on.
A while later, you apply for another financial product or service and come across the familiar request for furnishing KYC details yet again. You already have your documents, your details have been verified, and you may wonder.. “Why do I need to share the same information again?”
This is where CKYC, or Central KYC, comes in.
It brings KYC records into a centralized system, making it possible for participating financial institutions to retrieve an existing KYC record when applicable.
But what exactly is CKYC, how does it work, and what are the documents required for CKYC?
Let’s understand it step by step.
What is KYC?
KYC stands for Know Your Customer.
It is the process through which a bank or other regulated financial institution establishes and verifies a customer's identity and address.
When you open a Savings Account, Current Account or establish another financial relationship, you may be asked to provide applicable identity and address information.
What is CKYC?
CKYC stands for Central KYC.
It refers to the centralised system through which KYC document records are maintained in the Central KYC Records Registry (CKYCR).
The registry is operated by the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI). Once a customer's KYC record is registered, a unique 14-digit KYC Identifier is generated. This is commonly called the CKYC Number.
This identifier provides a common reference to your central KYC record.
In simple terms:
KYC is the process. CKYC is the centralised record system. The CKYC Number identifies your record.
Where applicable, a participating financial institution can use the CKYC Identifier to retrieve your existing KYC record post seeking explicit consent from you, subject to the relevant requirements.
Why CKYC?
A person's financial journey can involve more than one financial relationship. Each one may require KYC information.
CKYC brings applicable KYC records into a common system.
If your KYC record is already available with CKYCR, a participating financial institution may retrieve it using your KYC Identifier (with your explicit consent), instead of collecting the same information again, wherever the applicable requirements allow it.
KYC vs CKYC
KYC:
- Means Know Your Customer
- Process of establishing and verifying customer information
- The financial institution collects and verifies the applicable information
CKYC:
- Means Central KYC
- Centralised system for storing KYC records
- The applicable KYC records are stored with CKYCR
How Does CKYC Work?
The process is simpler than the terminology may make it sound.
1. You provide your KYC details
The financial institution collects the information and documents required for your KYC.
2. Your information is verified
The institution verifies the details according to the applicable KYC requirements.
3. Your KYC record is submitted
Upon opening of relationship, the financial institution uploads the relevant KYC documents to CERSAI in the prescribed format.
4. A KYC Identifier is generated
A unique 14-digit KYC Identifier is generated once the record is registered.
5. The Identifier is communicated to you
The concerned institution communicates the identifier to you.
6. The record can be retrieved later
A participating financial institution can retrieve the existing KYC documents record using the KYC Identifier with customer’s explicit consent, subject to applicable requirements.
Which Documents are available with CKYCR?
The documents updated in CKYCR can vary depending on the customer and the financial relationship customer has opened with the financial institution.
For an individual, applicable KYC requirements may include recognised identity and address documents such as:
- Passport: Identity and address information
- Driver’s License: Identity and address information
- Voter's Identity Card: Identity and address information
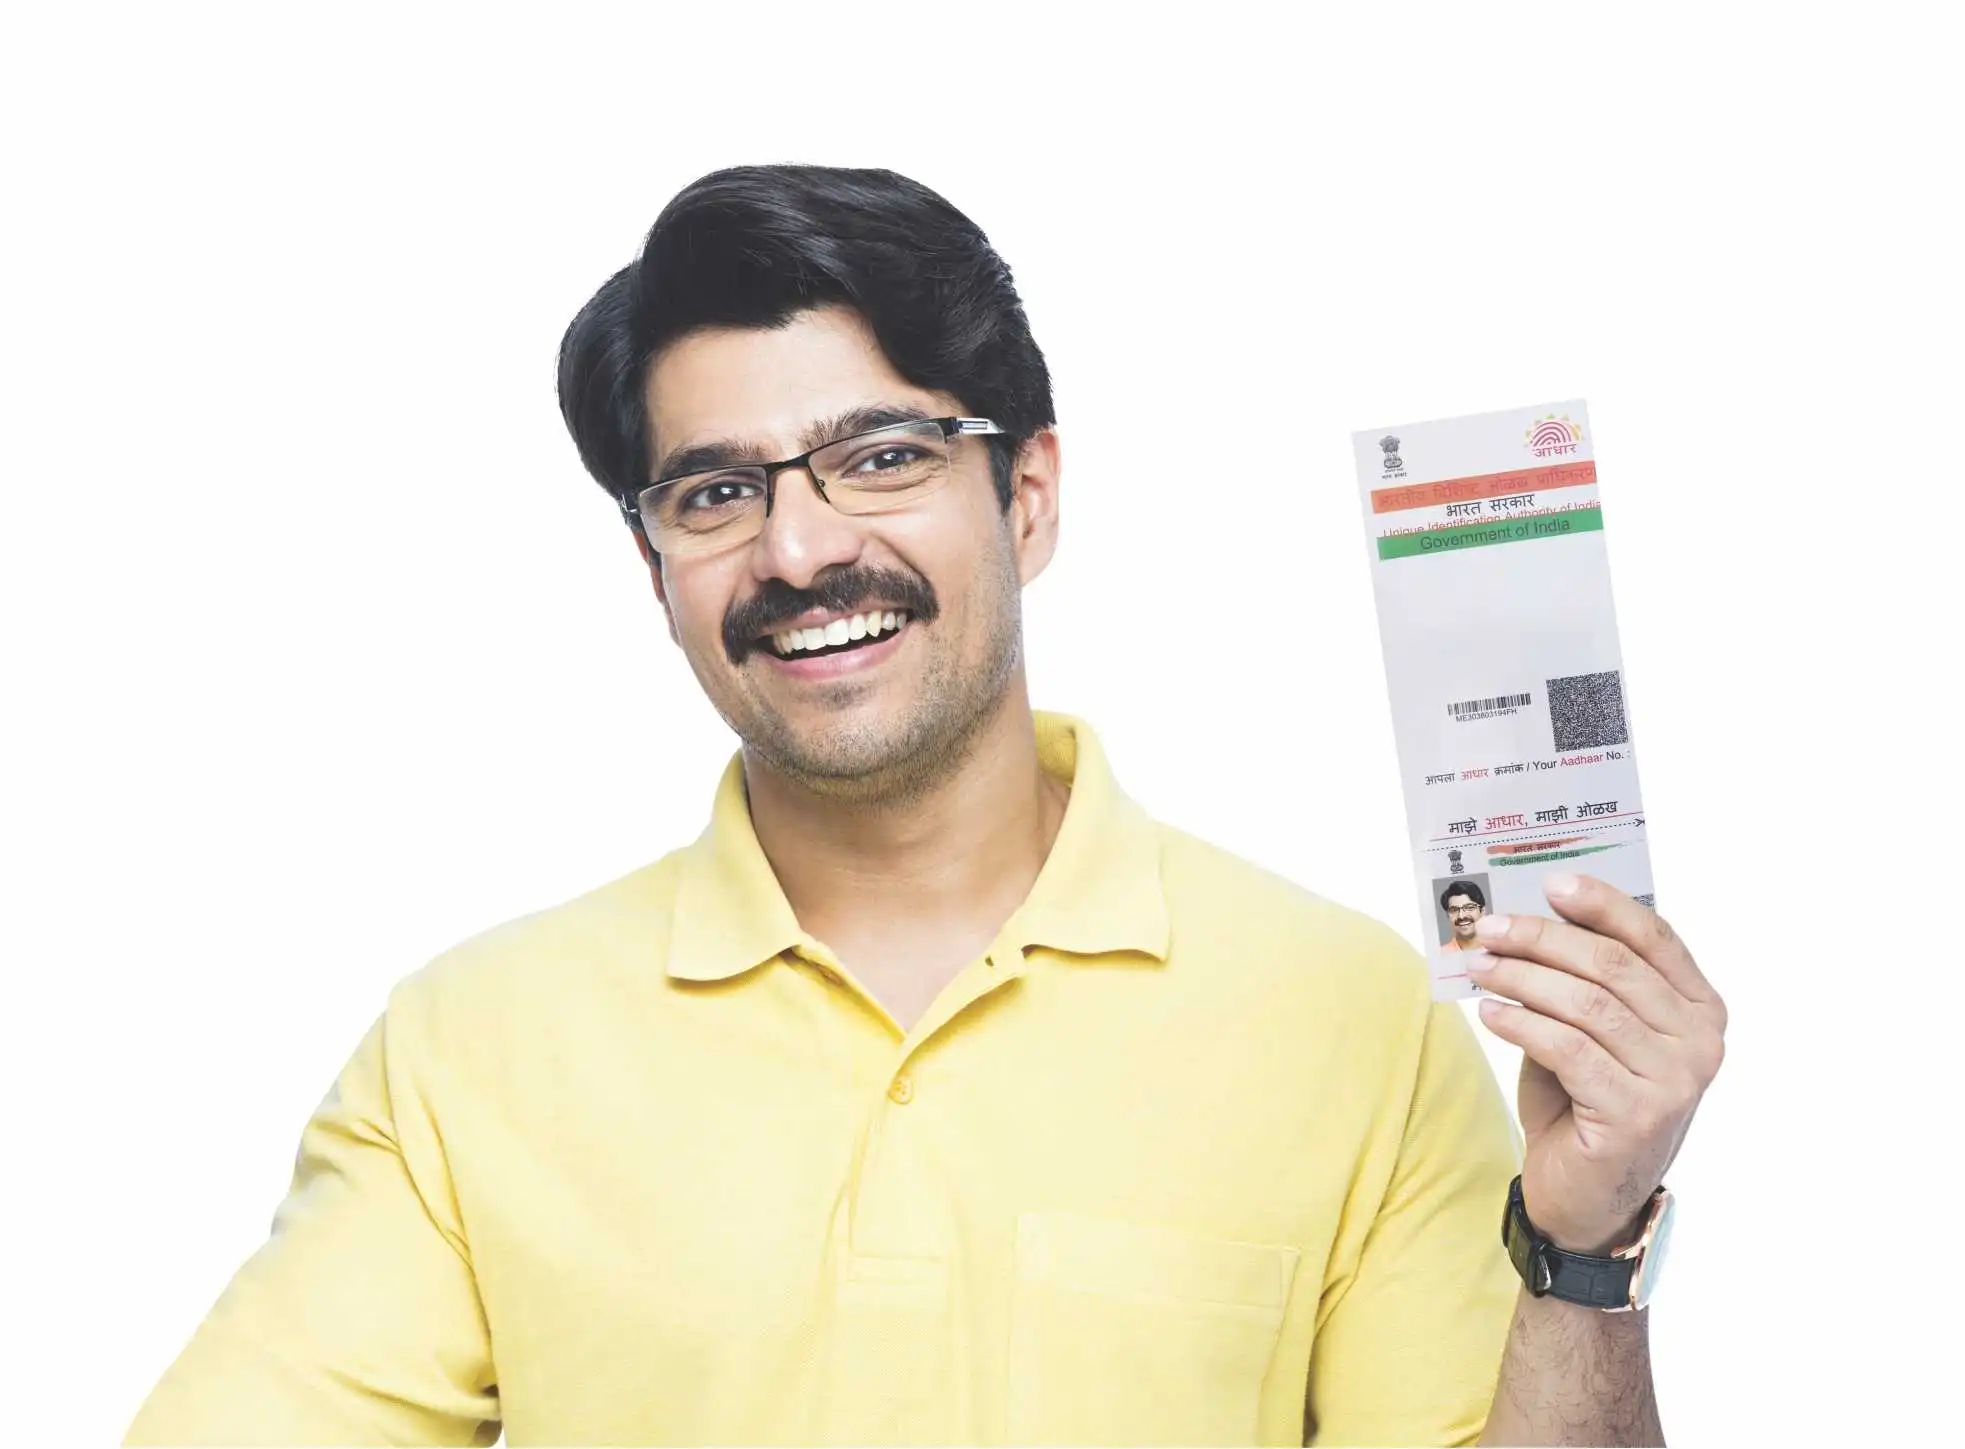
- Proof of possession of Aadhaar number: Subject to applicable requirements and in masked status
- NREGA Job Card: Where applicable
- National Population Register letter: Name and address information
PAN or Form 60 may as applicable
The exact documents required can differ, so the concerned financial institution will communicate the applicable requirements.
The documents required for entities differ as per the constitution of the entity
What are the Different Types of CKYC Accounts?
CKYC records can fall under categories based on the applicable KYC requirements.
- Normal Account: Standard KYC category
- Simplified Measures Account: For customers covered under specified simplified KYC measures
- Small Account: For accounts covered under relevant Small Account provisions
The applicable category depends on the customer's circumstances and the relevant KYC requirements.
How to Check CKYC Number Online?
Your CKYC Number is the 14-digit KYC Identifier linked to your central KYC record.
When a CKYC record is created, the concerned institution communicates the KYC Identifier to you.
If you cannot find your CKYC Number, you can contact the financial institution through which your KYC was completed to understand the applicable process for checking or confirming it.
Alternatively, you can give a missed call on 7799022129 from your registered mobile number to receive the CKYC number through SMS.
You can also log into Digi Locker, search for CKYCR and enter your PAN or Registration details to fetch your CKYC number.
It is also useful to remember that CKYC and KRA KYC are different systems. KRA KYC operates within the securities market framework, while CKYCR is the central repository under the Central KYC framework.
What does CKYC mean for an existing customer?
Having a CKYC Number does not mean your KYC information stays unchanged forever.
If your address or another relevant detail changes, your KYC information may need to be updated. Additional information or documents may also be required if the existing record is incomplete or your existing OVD (Officially Valid Document) is expired or further verification is applicable.
This is why keeping your KYC information current remains important.
How long is CKYC valid?
A CKYC Number is an identifier linked to your KYC record rather than a document with a fixed expiry date.
Your KYC information may need to be updated periodically or when relevant details change/ documents expire, depending on the applicable requirements.
Is CKYC mandatory for bank accounts?
KYC is required when establishing an account-based relationship with a bank, as per the applicable regulatory framework.
The applicable framework also provides for the use of the KYC Identifier and updation of relevant KYC records to CKYCR as prescribed.
The specific requirements can vary depending on the customer and the type of account.
How many types of KYC are there?
You may come across different KYC terms while dealing with financial institutions:
- Physical KYC: KYC completed through the applicable physical process
- e-KYC: KYC completed through an eligible electronic process
- Video-based KYC: Customer identification through a permitted video-based process
- Central KYC (CKYC): KYC information registered and maintained through CKYCR
The key difference is that CKYC refers to the centralised maintenance and retrieval of KYC records, rather than simply another way of submitting KYC documents.
CKYC
What happens after your KYC is registered?
- KYC verification: DCB Bank verifies your information as per the applicable KYC requirements.
- Registration with CKYCR: Where applicable, the relevant KYC information is submitted to the Central KYC Records Registry.
- CKYC Number generation: A unique 14-digit KYC Identifier, commonly known as the CKYC Number, is generated when the record is registered.
- Record retrieval: Where permitted and applicable, participating financial institutions can use the KYC Identifier to retrieve your existing KYC record basis your explicit consent.
CKYC makes the KYC process more streamlined by creating a central record that can be accessed by participating financial institutions when applicable. For DCB Bank customers, completing and keeping KYC details updated is an important part of maintaining a smooth banking relationship.
Disclaimer
Information on the website is for informational purposes only and does not constitute financial advice. Readers are advised to consult financial professionals for personalized advice before making decisions. The information on this blog is subject to change without notice and may become obsolete. DCB Bank reserves the right to modify, update, or remove content at any time. Savings Account and Fixed Deposit Interest rates are subject to change without prior notice. DCB Bank shall not be responsible for any direct / indirect loss or liability incurred by the reader for taking any financial decision based on the contents and information mentioned in this blog. By accessing and using this blog, users agree to adhere to these terms and conditions. For complete terms and conditions, please click here or to read the complete disclaimer of DCB Bank, please click here








DCB Customer Care


Follow us on


Download DCB Mobile Banking App